Is a Debt Relief Order the same as a Debt Management Plan?
Debt Management Plan against Debt Relief Order on duration, cost, your home, your credit file and what gets written off. An honest comparison, with the risks of both.
You never have to pay for debt advice. MoneyHelper (government-backed), StepChange, National Debtline and Citizens Advice all give free, confidential advice with no obligation. We would rather you got good advice somewhere than bad advice from anyone.
The comparison in full
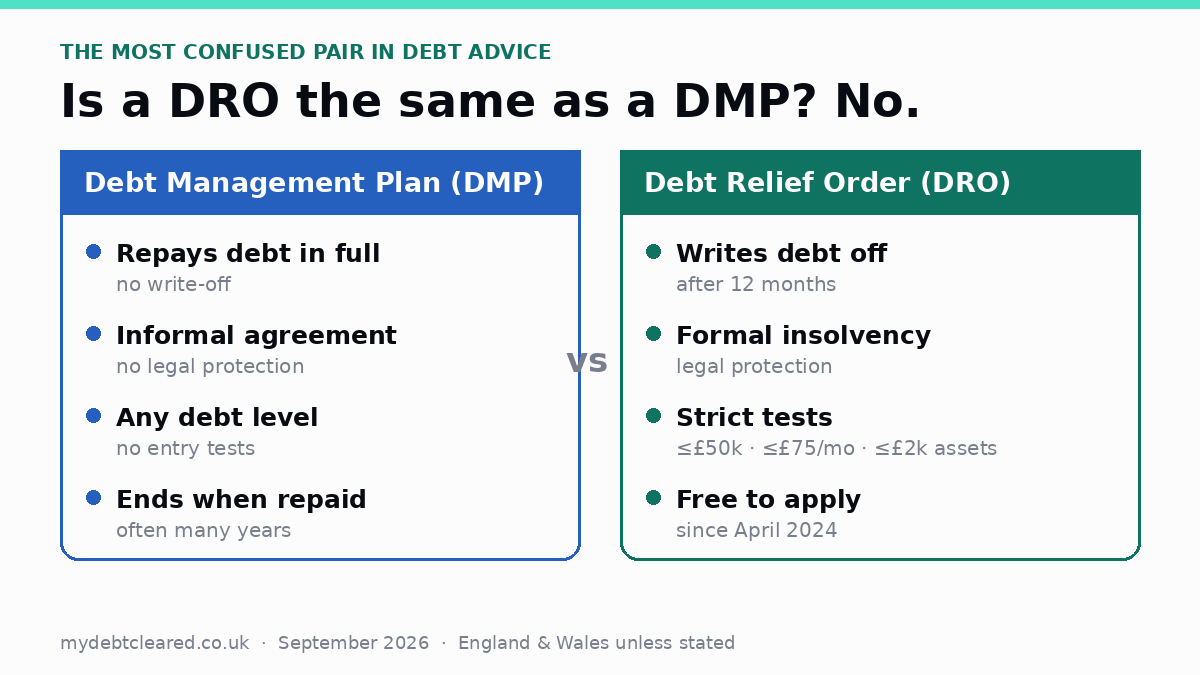
| Debt Management Plan | Debt Relief Order | |
|---|---|---|
| Legally binding on creditors | None — entirely voluntary | Full protection, then write-off |
| Duration | Until the debt is repaid — no fixed end | 12 months |
| What you pay | Monthly, flexible, changeable | No payments at all |
| Cost to you | Free providers available | Free — no application fee |
| Your home | Not affected | Not available to homeowners |
| Credit file | Defaults recorded, 6 years each | 6 years from the order date |
| Public record | No | Yes — Listed on the public Individual Insolvency Register. |
| Debt written off | No | Yes, at the end of the term |
| Where it applies | The whole of the UK | England and Wales (Northern Ireland has its own version with different thresholds) |
Factors an authorised adviser weighs when assessing Debt Management Plan
People whose difficulty is temporary or whose debts are repayable in a reasonable period, and who want to avoid insolvency, protect a professional role, or keep the flexibility to change their mind.
Factors an authorised adviser weighs when assessing Debt Relief Order
People on a low income with few assets and no realistic prospect of repaying. You must apply through an approved intermediary — usually a free debt advice charity. You cannot apply directly.
The verdict
The dividing line is your spare income. If you have £75 a month or less after essential costs, few assets and no property, a DRO exists precisely for you. If you have more than that, a DRO is closed and a DMP becomes one of the sensible options. Free advisers assess both, which is why starting with StepChange or Citizens Advice costs you nothing and rules one of them out quickly.
Risks on both sides
- Creditors are not obliged to freeze interest, and some do not. The balance can grow while you pay.
- No legal protection — court action and enforcement remain possible.
- Long plans can run for a decade or more, which is often worse than a formal solution.
- Your credit file is still damaged by the reduced payments.
- The thresholds are strict and absolute. Go over any one of them and you are ineligible.
- If your circumstances improve during the 12 months, the order can be revoked and the debts come back.
- It is a public record.
- You cannot get another DRO for 6 years.
Still weighing these two up?
Answer eight questions and we will show you which framework applies where you live and which routes fit the shape of your finances. It is not an eligibility check — it is a shortcut to the right reading.
Related guides
We are a marketing introducer. We publish information and, if you ask us to, we pass your details to an FCA-authorised debt advice firm we work with so they can contact you. We do not give debt advice, we do not provide debt solutions, and we do not decide whether any solution is right for you. We are paid by the firms we introduce people to, never by you. Read exactly how we make money.